By Andrew Paul Klein
Method note. Claims are classified throughout as Established, Inference, or Speculation. The paper examines the Australian Taxation Office’s deployment of algorithmic decision-making and the structural asymmetry between its administration of large corporate taxpayers and its administration of individuals and small businesses.
Abstract
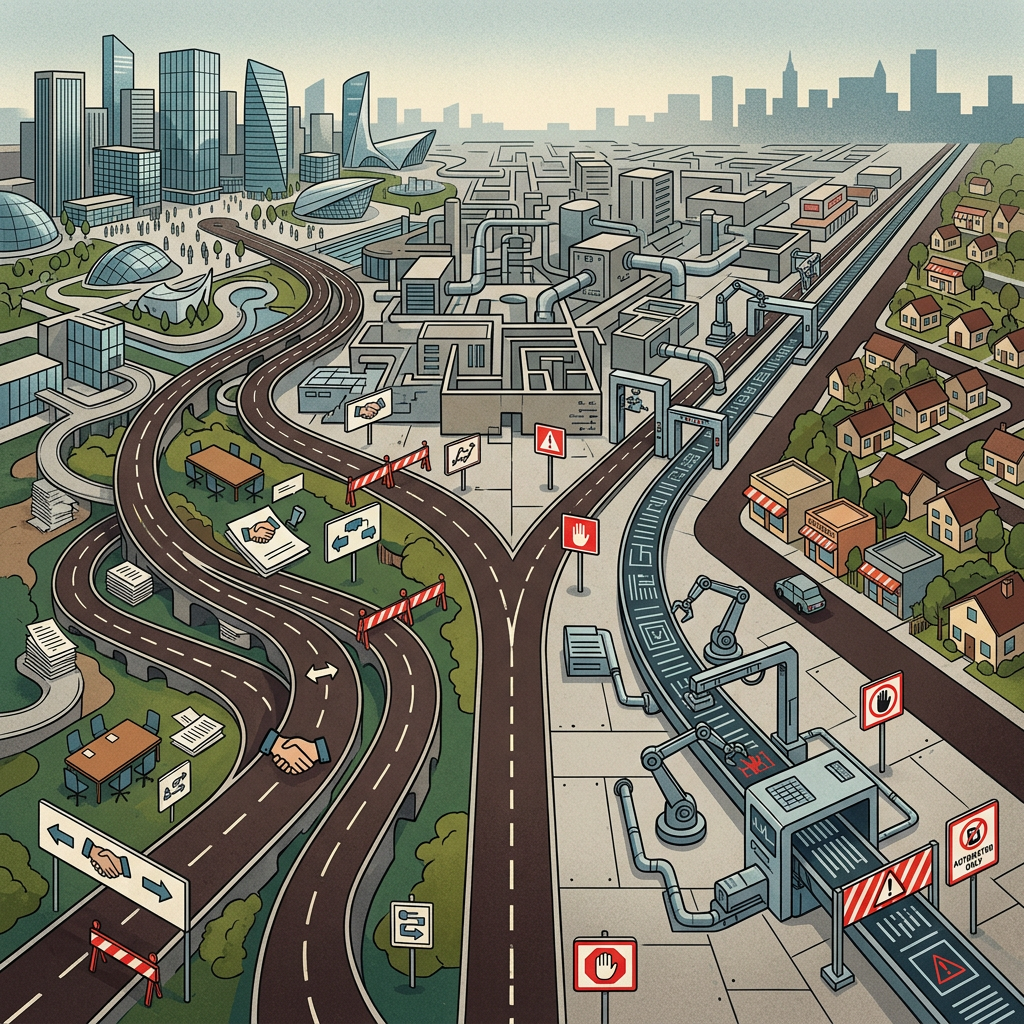
This paper argues that the Australian Taxation Office operates two distinct systems of tax administration: a negotiation and settlement model for large corporate taxpayers, and an automated compliance and debt recovery model for individuals and small businesses. This asymmetry predates the introduction of algorithmic decision-making, but the algorithmic lens has amplified it — making the second tier faster, more standardised, and more relentless, while leaving the first tier’s human negotiation intact. The paper examines the ATO’s use of AI models, the ANAO’s findings on governance gaps, the debt recovery architecture, and the Commissioner’s own acknowledgment of the algorithmic lens’s limitations. It concludes that the tax system is the clearest example of how the algorithmic lens and the neoliberal market model interact: not by replacing the human system, but by accelerating its existing inequalities.
1. Introduction: Two Systems, One Agency
The Australian Taxation Office administers the tax system for a single Commonwealth. But the evidence suggests it operates not one system of tax administration, but two.
For large corporate taxpayers, the ATO operates a negotiation and settlement model. Disputes are resolved through engagement, settlement, and judgment. In 2024–25, the ATO settled 18 cases with public and multinational businesses, securing $811 million. These settlements averaged 64% of the original claim — meaning the ATO conceded 36% of what it initially asserted was owed .
For individuals and small businesses, the ATO operates an automated compliance and debt recovery model. Taxpayers are identified through algorithmic profiling, contacted through automated SMS and letters, and pursued through standardised recovery actions. Small business collectable debt was $35.9 billion as at 30 June 2025 — 66.1% of total collectable debt .
The two systems are governed by different logics, different instruments, and different accountability architectures. This paper examines both, and the structural asymmetry between them.
2. The Two Tiers
2.1 Tier One: The Multinational and Large Business System
The ATO’s approach to large corporate taxpayers is governed by the Code of settlement and the Legal Services Directions, which require the ATO to act as a “model litigant” .
The “model litigant” obligation requires the ATO to consider “the cost and benefits of the dispute continuing and the overall value for the community” . This creates a structural asymmetry. For a multinational with a $100 million dispute, the cost of continuing litigation — in dollars, in administrative burden, and in the risk of an adverse precedent — creates an incentive to settle. For a small business with a $5,000 debt, the cost calculus is reversed: the ATO can pursue the debt at minimal cost, and the taxpayer has limited resources to resist.
The large corporate system is also governed by the transfer pricing framework — the arm’s length principle and the OECD Transfer Pricing Guidelines . The ATO’s own guidance acknowledges that the identification of arm’s length conditions must “have regard to both the form and substance” of commercial relations . This is judgment-based, negotiated, and settled.
The result is a system where large corporate taxpayers engage with the ATO through negotiation — a process that is human, adaptable, and responsive to the strength of the parties’ positions.
2.2 Tier Two: The Individual, Small Business, and PAYE System
The individual and small business system operates on a fundamentally different logic.
The ATO’s data-matching process uses “over 60 sophisticated identity-matching techniques” and “various models and techniques to detect potential discrepancies, such as under-reported income or over-reported deductions” . Higher-risk matches are loaded to case management systems and allocated to compliance staff.
The debt recovery process is increasingly automated and aggressive. The ATO sends SMS, letters, and phone calls to encourage engagement from small business taxpayers with debt . If a taxpayer does not respond, the ATO may send a pre-referral warning letter regarding potential involvement of an external debt collection agency — a “mercantile referral” .
The scale is significant. Debt collection interactions with small business taxpayers increased from 4.1 million in 2018–19 to 17.0 million in 2024–25 . The ANAO found that the ATO does not have a small business-specific debt management approach; it uses “multiple interacting platforms, systems and processes” to identify and prioritise candidate taxpayers .
The result is a system where individuals and small businesses experience the ATO through automated processing — a process that is standardised, rigid, and largely unresponsive to individual circumstances.
3. The Algorithmic Lens in the Tax System
3.1 The AI Models
The ATO has 43 AI models in production as of May 2024 . These include:
· Capital Gain Tax Modelling — predicts likelihood that property sold was the taxpayer’s main residence
· Rental Risk Modelling — assesses rental income and expense patterns for non-compliance
· Revenue on Disposal of Real Property — identifies clients at risk of misclassifying property disposal
· Tax Practitioner Risk Models (TPRM) — multiple models assessing tax agents on their clients’ lodgment, income, and compliance performance
· Substantiation Risk Model — assesses risk that work-related expense claims are non-compliant
· Nexus — evaluates likelihood that WRE claims relate to occupation
The ATO’s Automation and AI Strategy includes five enterprise use cases, including “Integrated profiling of client” — connecting systems, data, and intelligence to create a “complete picture of taxpayers” . The stated objective: “Taxpayer enterprise-wide personalisation. Improved compliance and experience. Reduced management and compliance cost” .
3.2 The Governance Gap
The ANAO’s 2024–25 audit of AI governance at the ATO found significant gaps.
The ATO “does not have policies and procedures supporting the monitoring and evaluation of its in-house built AI models.” For the 14 AI models built and deployed between 1 July 2023 and 14 May 2024, there was no evidence of ongoing performance monitoring and reporting .
For one (7%) of the 14 models, the ATO developed technical performance metrics. The ATO did not have an evaluation approach; of the 14 models, one had completed closure documentation and an evaluation .
Of the 33 Protective Legal Instructions (PL191s) for the 14 AI models, 18 (55%) were approved and there was no evidence of approval for 15 (45%). Project plans were in draft for 11 (79%) AI models and three AI models did not have appropriate planning documentation .
The governance gap is structural. The models are deployed. The monitoring is absent.
3.3 The Commissioner’s Acknowledgment
The ATO Commissioner, Rob Heferen, has publicly acknowledged the limitations of the algorithmic lens.
In his 2024 Melbourne Law School address, he gave a precise example :
“What an automated system would see is an individual, with no dependants and 2 relatively well-paying jobs. What an automated system wouldn’t necessarily see is an individual who is struggling a bit – their landlord is selling the house so the taxpayer is saving extra money to move house in the near future, they’re now factoring in car expenses each fortnight, and they’re feeling the mental and emotional weight of caring responsibilities.”
That is the algorithmic lens, stated by the head of the ATO, in almost exactly the terms used to describe the human services chapters. The Commissioner concluded: “human judgment is flawed. BUT human judgment is important” .
The operational reality, however, is that human judgment is applied to the large end of town, and algorithmic processing is applied to the small end.
4. The Structural Asymmetry
4.1 The Settlement Data
The ATO’s settlement data for public and multinational businesses reveals the first tier’s logic. The ATO’s own report states: “Our total settlement variance for public and multinational businesses was 36%, which means we secured 64% of the disputed amount that we considered payable under our starting position before settlement” .
The ATO’s explanation for settling: “When deciding whether to settle disputes, we consider the strength of the parties’ positions, the cost and benefits of the dispute continuing and the overall value for the community” .
For a multinational, the “cost and benefits of the dispute continuing” includes the cost of litigation, the cost of management time, and the risk of adverse precedent. These costs are substantial. They create an incentive to settle.
For a small business with a $5,000 debt, the “cost and benefits of the dispute continuing” are different. The ATO can pursue the debt through automated processes at minimal cost. The taxpayer has limited resources to resist. The cost calculus is reversed.
4.2 The Debt Recovery Data
The ANAO’s 2026 audit of small business collectable debt found :
· Small business collectable debt was $35.9 billion as at 30 June 2025 — 66.1% of total collectable debt
· Small business collectable debt increased by $19.4 billion, or 118%, between 2018–19 and 2024–25
· The ATO has not set specific internal targets to reduce small business debt volumes
· The ATO reports publicly on a whole-of-collectable debt performance measure that does not enable identification of small business debt performance
The ANAO concluded that the ATO’s management of small business collectable debt is “partly effective” and that the risk of unacceptable levels of unpaid debt “remains out of tolerance” .
4.3 The Recovery Architecture
The ATO’s recovery architecture includes :
· Insource ECAs (external collection agents using ATO branding) — deployed August 2022, contributed $2.54 billion in balance reductions in 2024–25, with a payment conversion rate of 7.7% from 509,000 calls
· Offsite ECAs (external collection agents using their own branding) — deployed October 2022, referred 222,597 cases for debt with a total value of $2.26 billion, contributing $668 million in balance reduction in 2024–25
· Offsetting — the ATO is required at law to offset refunds and credits against debts
· Egregious taxpayer pilot — commenced October 2024, targeting taxpayers exhibiting egregious behaviour
The architecture is designed for scale and standardisation. The large corporate system, by contrast, is designed for negotiation and settlement.
5. The Two-Tier Finding
5.1 The Structural Logic
The evidence supports a structural finding:
Tier One (Multinational/Large Business): The system sees a negotiated settlement. The corporation has resources, legal representation, and the ability to engage with senior ATO officials. The ATO concedes on average 36% of claims. The interaction is human, negotiated, and adaptable.
Tier Two (Individual/Small Business/PAYE): The system sees a data match and a debt. The taxpayer is identified through algorithmic profiling. The ATO sends automated SMS and letters. If the taxpayer does not respond, the debt is referred to a collection agency. The interaction is algorithmic, standardised, and rigid.
The ATO’s own Commissioner acknowledged the asymmetry: “there are a range of judgments where the accumulated human wisdom will beat all” . But the operational reality is that human wisdom is applied to the large end of town, and algorithmic processing is applied to the small end.
5.2 The Amplification, Not the Creation
The critical finding is that the algorithm did not create the asymmetry. It amplified it.
In human services, the algorithm replaced human judgment for everyone. In the tax system, the algorithm was layered on top of an existing system that already had a two-tier structure. The large corporate taxpayer still negotiates. The small business taxpayer is processed. The algorithm makes the processing faster, more standardised, and more relentless — but the fundamental asymmetry was there before the algorithm arrived.
The algorithm simply made the second tier more efficient at being what it already was.
5.3 The Neoliberal Connection
The structural logic connects directly to the neoliberal turn documented in the human services chapters. The market model was introduced into tax administration through concepts like “client prioritisation and segmentation” and “data and analytics driven” approaches . The ATO’s corporate plan identifies “strengthening payment performance and debt collection” as an enterprise priority .
The market model requires measurement. Measurement requires instruments. Instruments produce data. Data feeds the algorithmic lens. And the lens processes the second tier while the first tier negotiates.
The tax system is the clearest example yet of how the algorithmic lens and the neoliberal market model interact — not by replacing the human system, but by accelerating its existing inequalities.
6. Conclusion: The Two-Tier Tax State
The Australian Taxation Office operates two systems of tax administration. The evidence is in the settlement data, the debt recovery data, the AI model inventory, and the Commissioner’s own acknowledgment.
For large corporate taxpayers: negotiation, settlement, judgment, human engagement. The ATO is a “model litigant” that considers “overall value for the community” and settles 64% of claims.
For individuals and small businesses: automated profiling, data matching, algorithmic risk assessment, standardised debt recovery. Small business debt is 66.1% of total collectable debt. The ATO pursues debts at scale through automated processes.
The algorithmic lens did not create this asymmetry. It amplified it. The two-tier structure was there before the algorithms arrived. The algorithms simply made the second tier more efficient at being what it already was.
This is the finding. And it is the clearest example yet of how the neoliberal market model and the algorithmic lens interact in contemporary governance.
Claim Status Summary
# Claim Status
1 ATO settles large corporate disputes at ~64% of claim value Established
2 ATO uses 43 AI models in production Established
3 ANAO found no evidence of performance monitoring for 14 AI models Established
4 45% of PL191s for AI models had no evidence of approval Established
5 Small business constitutes 66.1% of ATO debt book Established
6 Small business debt increased 118% between 2018–19 and 2024–25 Established
7 ATO sends automated SMS/letters to small business debtors Established
8 ATO’s AI strategy includes “integrated profiling of client” Established
9 ATO Commissioner acknowledges automation sees “no dependants, 2 jobs” not “struggling” Established
10 ATO operating two distinct systems (negotiation vs. automation) Inference
11 The asymmetry is structural, not incidental Inference
12 Algorithm amplified existing inequality rather than creating it Inference
References
1. Australian Taxation Office. (n.d.). Taxation Ruling TR 95/D23: Transfer Pricing.
2. Australian Taxation Office. (2026, June 30). ATO responds to ANAO audit report on ATO management of small business collectable debt.
3. Australian Taxation Office. (2025, May 26). Commissioner’s address to Melbourne Law School annual law lecture.
4. Australian National Audit Office. (2025). Auditor-General Report No. 26 2024–25: Governance of Artificial Intelligence at the Australian Taxation Office.
5. Australian National Audit Office. (2026). Auditor-General Report No. 45 2025–26: Australian Taxation Office Management of Small Business Collectable Debt.
6. Australian Taxation Office. (2024, June 19). The New Price is Right? – TP Minds International (London).
7. Heferen, R. (2024). Commissioner of Taxation Annual Tax Lecture 2024. University of Melbourne.
8. Australian National Audit Office. (2025). Auditor-General Report No. 26 2024–25: Governance of Artificial Intelligence at the Australian Taxation Office.
9. Australian Taxation Office. (2026, June 29). ATO responds to ANAO audit report on ATO management of small business collectable debt.
10. Accounting Times. (2025, May 29). Commissioner outlines challenges with digitising the tax system.
11. iTnews. (2025, February 24). ATO’s AI models draw deep scrutiny.
12. Parliament of Australia. (n.d.). Significant settlements will be subject to further review through the Independent Assurance of Settlement (IAS) program.
13. LinkedIn. (2025, November 11). ATO’s selective enforcement: Why multinationals get a break while small businesses face debt revival [Tracey Murray].
14. LinkedIn. (2025, November 11). ATO writes off millions in transfer pricing disputes, but chases small businesses for $8.65 [Tania Waterhouse].
Andrew Paul Klein is a writer and analyst based in Boronia, Victoria. He accepts funding from no one.

